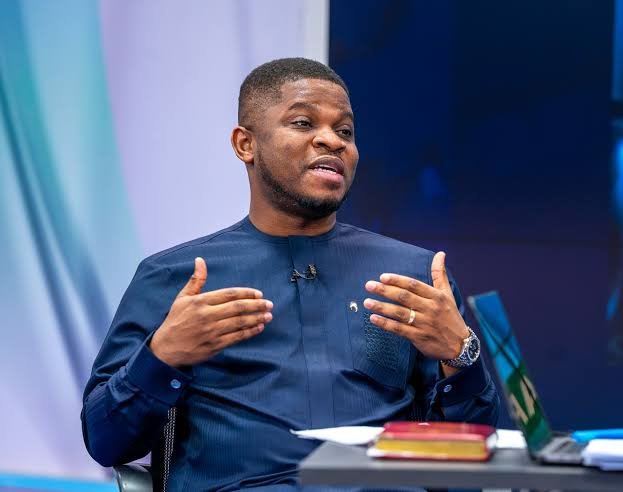
GoldBod Chief Executive Officer Sammy Gyamfi has rejected claims that the Ghana Gold Board failed to give the Auditor-General complete financial information for its 2025 accounts, insisting that the audit team had unrestricted access to the documents required for its work.
Mr Gyamfi made the comments on Wednesday, August 19, 2026, during the government’s accountability series, in response to questions surrounding GoldBod’s reported GH¢5.44 billion overall surplus for the 2025 financial year.
The dispute centres on whether GoldBod’s audited financial statements provide a complete picture of the institution’s financial position.
Minority Leader Alexander Afenyo-Markin has questioned the GH¢5.44 billion surplus reported by GoldBod and suggested that the Auditor-General may not have received all the information necessary to fully assess the institution’s operations.
Mr Gyamfi has rejected that suggestion.
He said the Auditor-General’s audit team had access to all relevant records and that GoldBod supplied the documents requested during the audit.
He also said issues raised by the auditors in the management letter were addressed by the institution.
According to the figures cited in the current debate, GoldBod recorded an operational surplus of GH¢909.7 million and an overall surplus of GH¢5.44 billion for the 2025 financial year.
The distinction between the two figures is important because they describe different aspects of the institution’s financial performance.
The GH¢909.7 million figure represents the operational surplus cited by GoldBod, while the larger GH¢5.44 billion figure is described as its overall surplus.
Mr Gyamfi said the Auditor-General had unrestricted access to relevant documents throughout the audit.
He further argued that the completed audit contained no adverse findings against GoldBod, including findings relating to alleged losses, procurement breaches or violations of the Public Financial Management Act.
His position is that questioning whether the Auditor-General received complete information effectively calls into question the credibility of an independent audit process.
He therefore challenged the media and critics to verify the issue directly with the Auditor-General and rely on the contents of the official audit report.
The Ghana Audit Service’s own description of the Auditor-General’s constitutional role states that the Auditor-General has access to books, records, returns and other documents relevant to public accounts. The Service also says the Auditor-General is constitutionally independent in performing the auditing function.
The key issue is not simply whether GoldBod reported a surplus. It is whether the figures were produced from complete financial records and properly examined through the statutory audit process.
That is why the contents of the Auditor-General’s actual report are important to the public debate.
GoldBod’s position, as presented by its CEO, is that the audit process was conducted with access to the necessary information and that no adverse findings were made against the institution.
The Minority’s concerns, however, represent a different position and should not be presented as established findings of the Auditor-General unless the relevant audit documents substantiate them.
For readers assessing the controversy, the clearest distinction is between what GoldBod’s CEO says about the audit and what the Auditor-General’s published report actually establishes.